Understanding your exact labor expenses is vital for maintaining healthy margins and pricing your products correctly. When you manufacture goods or assemble physical inventory, human effort is rarely a flat fee; it scales directly with output. A direct labor cost per unit calculation reveals precisely how much wages, payroll taxes, and benefits go into producing a single item. Without this metric, businesses often underprice custom goods, underestimate labor drain, or miscalculate their true break-even point. Whether you run a small custom woodworking shop, a textile studio, or a light assembly business, mastering this math ensures your revenue covers both materials and hands-on time.
On this page, we explore the core mechanics of labor costing, define every variable involved, walk through detailed numerical examples, and help you integrate these calculations into a broader financial strategy. For related operational expenses, you can also explore tools like the Break-Even Calculator to see how labor feeds into your overall sales volume targets.
What is Direct Labor Cost Per Unit?
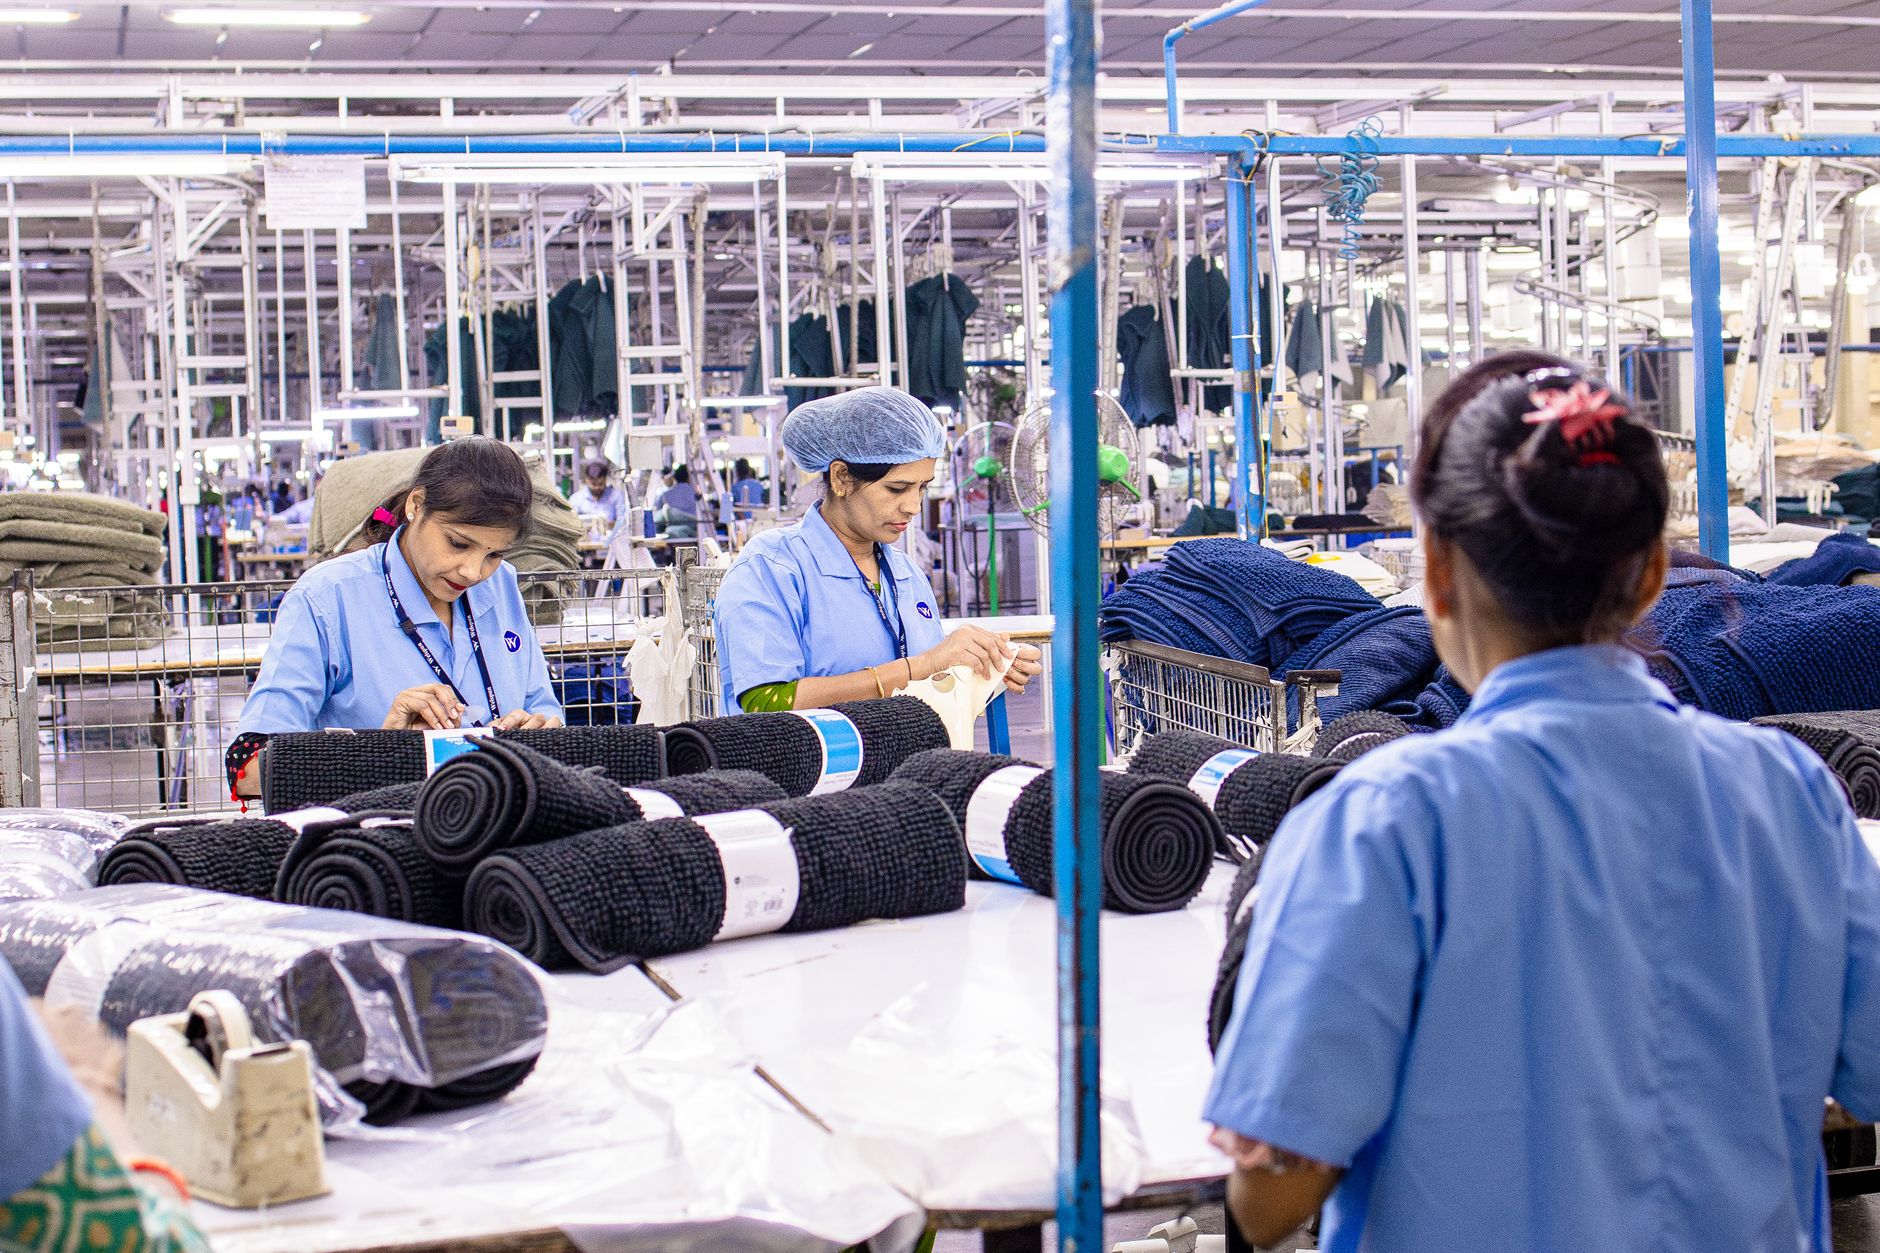
Direct labor cost per unit represents the total wages and associated payroll overhead paid to production workers specifically for the time spent creating a single finished product. In business accounting, direct labor is distinct from indirect labor. Direct labor includes workers who physically touch, assemble, or craft the item. Indirect labor includes supervisors, maintenance staff, and administrative personnel whose time cannot be easily traced to a single unit of output.
When calculating unit costs, businesses must look beyond base hourly wages. True labor cost includes mandatory employer payroll taxes, workers' compensation insurance, and any direct benefits tied to hours worked. By dividing the total cost of this direct labor pool over a specific period by the number of units produced during that same period, you arrive at your baseline direct labor cost per unit.
Failing to distinguish between direct and indirect labor leads to inaccurate job costing. For instance, if an artisan spends four hours crafting a mahogany chair, those four hours are undeniably direct labor. However, if the shop foreman spends four hours managing inventory lists, supervising multiple teams, and coordinating shipping schedules, that time is indirect labor and must be absorbed through general overhead allocation rather than individual unit direct costing. Clear boundaries ensure that your pricing accurately reflects the actual human effort required to bring a specific product to completion.
The Direct Labor Cost Per Unit Formula
The standard mathematical formula used to determine your unit labor expense is straightforward, though gathering accurate inputs requires careful record-keeping. The formula is expressed as:
Direct Labor Cost Per Unit = Total Direct Labor Costs / Total Units Produced
To break this down further, let us define each component clearly:
- Total Direct Labor Costs: The sum of all wages, payroll taxes, and mandatory benefits paid to production staff over a specific timeframe (e.g., one week or one month).
- Total Units Produced: The total number of finished, sellable goods successfully manufactured during that exact same timeframe.
Alternatively, if you track production by time per unit rather than aggregate totals, you can use the hourly rate approach:
Direct Labor Cost Per Unit = Fully Burdened Hourly Labor Rate × Time Required to Produce One Unit (in hours)
The fully burdened hourly rate includes the worker's base pay plus employer taxes and mandatory insurance divided by total productive hours. Furthermore, expanding this mathematical framework allows businesses to test scenarios involving productivity gains. If you invest in new assembly tools that reduce the time required to build a unit from 30 minutes to 20 minutes, your unit labor cost decreases proportionally, even if employee wages remain constant.
Step-by-Step Guide to Calculating Unit Labor Costs
Gathering your business data and applying it to the formulas requires a structured sequence. Follow these steps to ensure absolute accuracy in your operational accounting:
- Define the Measurement Period: Choose a consistent timeframe, such as a standard 40-hour work week or a monthly accounting cycle, to align labor expenses with output counts.
- Identify Direct Production Staff: List only the employees whose daily work directly contributes to manufacturing the physical product, excluding management and support roles.
- Calculate Fully Burdened Wages: Add up hourly pay or salaries, then add employer-paid taxes (like FICA in the US), mandatory insurance, and benefits tied directly to their hours.
- Measure Total Output: Count the exact number of completed, quality-checked units produced during that period. Exclude spoiled or scrapped items unless your business model explicitly absorbs waste into standard pricing.
- Compute the Ratio: Divide total labor expenses by total units produced to find your baseline cost per unit.
- Review and Adjust: Compare your calculated unit cost against historical benchmarks and industry standards to identify anomalies or opportunities for efficiency improvements.
Worked Example 1: Custom Leather Goods Workshop
Imagine a small leather crafting workshop that produces handmade leather wallets. The owner employs two craftspeople who work 40 hours per week each, totaling 80 direct labor hours per week.
Input Data:
- Base wage for craftspeople: $20.00 per hour
- Employer payroll taxes and worker compensation insurance overhead: $5.00 per hour
- Fully burdened hourly labor rate: $25.00 per hour ($20 + $5)
- Total weekly direct labor hours: 80 hours
- Total wallets produced in that week: 160 wallets
Calculation:
First, find the total weekly direct labor cost:
Total Weekly Cost = 80 hours × $25.00/hour = $2,000.00
Next, apply the direct labor cost per unit formula:
Direct Labor Cost Per Unit = $2,000.00 / 160 wallets = $12.50 per wallet
This means every single wallet incurs $12.50 in pure labor expense before accounting for leather hides, thread, packaging, or overhead costs like rent and electricity. If the workshop owner wants to keep electricity and facility expenses clear, they can also review tools like the Electricity Cost Calculator to evaluate facility overhead.
To extend this analysis, suppose the workshop receives an order for an additional 40 wallets. If the craftspeople must work overtime at a rate of time-and-a-half ($30 base wage plus $5 burden = $35 burdened hourly rate), the labor cost for those extra units increases. Calculating marginal labor cost prevents businesses from accepting rush orders that actually diminish overall profitability due to unexpected overtime premiums.
Worked Example 2: Small Batch Assembly Operation
Consider a small business assembling electronic sensor modules. The assembly process is measured by time per unit rather than aggregate weekly totals.
Input Data:
- Fully burdened hourly operator rate: $22.00 per hour
- Time required to assemble one sensor module: 15 minutes (0.25 hours)
Calculation:
Using the hourly rate and time formula:
Direct Labor Cost Per Unit = $22.00 × 0.25 hours = $5.50 per module
This method allows the business owner to instantly estimate labor costs when taking custom orders of varying quantities without waiting for end-of-month payroll summaries.
Taking this example a step further, suppose the business scales up production and introduces batch processing. If an operator can assemble four modules simultaneously in 40 minutes (0.667 hours), the direct labor cost per unit changes dramatically:
Total time for batch of four = 0.667 hours
Total labor cost for batch = 0.667 hours × $22.00 = $14.67
Direct Labor Cost Per Unit = $14.67 / 4 modules = $3.67 per module
This demonstrates how process optimization and batching can lower per-unit labor costs, giving small businesses greater flexibility in tiered pricing and wholesale negotiations.
Interpreting Your Results and Pricing Strategy
Once you calculate your direct labor cost per unit, you must integrate it into your pricing architecture. Total product cost is generally calculated as:
Total Product Cost = Direct Materials + Direct Labor + Allocated Manufacturing Overhead
If your direct labor cost is $12.50, your raw materials cost is $15.00, and your allocated overhead is $7.50, your total cost to produce one unit is $35.00. Selling the item below this threshold guarantees a net loss on every sale. To achieve a healthy profit margin, your selling price must comfortably exceed this total cost.
When labor costs consume an unexpectedly high percentage of your product price, you face two primary choices: improve workflow efficiency to reduce time-per-unit or adjust your retail pricing upward. For broader financial planning, combining labor data with your operating expenses helps you utilize a Break-Even Calculator to determine exactly how many units you must sell each month to cover all fixed and variable business costs.
Furthermore, understanding your unit labor cost helps you evaluate target profit margins. If your industry standard demands a 50% gross margin, you cannot rely on guesswork. Every penny saved in production efficiency drops straight to your bottom line, increasing your operational resilience against fluctuating material prices or supply chain disruptions.
Common Mistakes in Labor Costing
Small business owners frequently miscalculate labor expenses by overlooking critical variables. Avoid these common operational traps:
- Ignoring Payroll Overhead: Counting only base hourly wages while omitting employer taxes, social security contributions, and mandatory insurances understates true labor expenses by 10% to 25%.
- Including Non-Productive Time: Failing to account for coffee breaks, shift handovers, tool setup, and general machine maintenance when calculating effective output per hour.
- Confusing Direct and Indirect Labor: Accidentally including the salary of a general manager or administrative assistant in direct unit labor calculations distorts product-specific costs.
- Using Flawed Production Counts: Dividing payroll costs by units started rather than units successfully finished and quality-approved. Scrapped units consume labor but generate no revenue.
- Overlooking Learning Curves: Assuming new employees instantly achieve peak production speed. Initial weeks often involve slower output, meaning temporary higher labor costs per unit until staff attain full proficiency.
Decision Checks for Small Business Owners
Before finalizing your pricing models or committing to large manufacturing runs, apply these operational decision checks to verify your numbers:
- Have you included all mandatory employer tax burdens in your hourly labor rate calculation?
- Are your production counts based strictly on finished, marketable goods rather than work-in-progress inventory?
- Does your pricing structure account for potential overtime rates if demand surges unexpectedly?
- Have you separated administrative and supervisory wages from direct assembly labor?
- Does your final unit price cover direct materials, direct labor, and a proportionate share of fixed overhead?
Frequently Asked Questions
What is the difference between direct and indirect labor?
Direct labor includes workers who physically manufacture or assemble the product. Indirect labor includes support staff, supervisors, and maintenance workers whose time cannot be directly traced to a single unit of output.
How do I include employee benefits in my labor rate?
Calculate the total annual cost of mandatory and voluntary benefits provided to production staff, divide it by total annual productive hours, and add that hourly figure to the base wage rate to create a fully burdened labor rate.
Should I include spoiled or defective units in my production count?
No. You should only divide labor costs by sellable, finished units. Including ruined items artificially lowers your apparent labor cost per good unit and misleads your pricing model.
How often should I recalculate my direct labor cost per unit?
You should review your unit labor costs whenever wages change, raw material handling changes, or production techniques are updated. At a minimum, many businesses audit their labor metrics quarterly.
Can salaried employees be included in direct labor costs?
Generally, direct labor is tracked on an hourly basis. However, if a salaried employee spends 100% of their working hours dedicated exclusively to manufacturing a specific product line, their prorated salary can be allocated to direct labor.
How does labor cost per unit affect my break-even point?
Labor cost per unit forms part of your variable cost structure. As labor costs rise, your total variable cost per unit increases, which raises the number of units you must sell to break even.
How do training periods impact direct labor calculations?
During training, employees produce fewer units per hour. To maintain accurate pricing, businesses often calculate separate training-period labor costs or absorb the initial efficiency deficit as a startup investment rather than skewing standard recurring unit costs.
What tools can help track direct labor hours accurately?
Digital time-tracking software, shop-floor barcode scanners, and job-costing mobile applications allow workers to clock in and out of specific batch orders, providing precise data for your calculations.
Conclusion
Calculating your direct labor cost per unit is a foundational step for any small business producing physical goods. By capturing fully burdened wages, tracking accurate output numbers, and avoiding common overhead omissions, you gain complete visibility into your production economics. Use these formulas to refine your pricing strategy, safeguard your profit margins, and build a more resilient, profitable business.
Found this calculator guide useful? Support more free tools.
Buy Me a Coffee
Comments
Post a Comment